Zambia’s power reforms win a second term
With the re-election of Zambia’s President Hakainde Hichilema to a second five-year term in August this year, investors and private power developers are hoping that the early optimism generated by the country’s National Energy Compact will be justified by second-term progress on tariff reform, open access to transmission and distribution for private developers and simplified licensing for private power projects.
Written for ENN by Richard Walker of FirstWord Media.
So far, the signs are promising, with investors expecting continuity for the reforms Zambia has already used to bring private capital into the power sector. However, both investors and developers will judge President Hichilema’s second term on whether transmission infrastructure can be built fast enough to carry the projects already in the pipeline.
“Following the recent election, I expect continuity rather than any fundamental change of direction,” says Jason De Carteret, chief executive of the UK-headquartered solar power developer Solarcentury Africa, which has completed over 59MW of Zambian solar generation projects with another 177MW in development. “The greater challenge for the new government will be implementation: completing the Open Access Framework, establishing transparent grid pricing and market rules, strengthening transmission and converting the very substantial project pipeline into operating capacity.”
The challenge and the ambition
Power shortages became a daily reality in Zambia when the drought of 2024 left the country’s hydropower generating plants (which until recently accounted for more than 80% of installed capacity) with too little water to deliver more than a fraction of potential output. Hydropower capacity has since begun to recover, with usable storage at Lake Kariba (the world’s largest artificial reservoir) at 37% as of 14 October, compared to 12.75% a year earlier. However, the Zambezi River Authority has cut next year’s allocation of water for power generation from 36 billion to 23 billion cubic metres on forecasts of poor rains and strong El Niño weather conditions.
Zambia is not the only African country to experience this kind of energy crisis through multiple causes, but it has treated the past few years as a wake-up call. Crisis became the catalyst for a new approach to power-sector investment, with the emphasis on transformation through renewables driven primarily by private investment. Zambia’s National Energy Compact (a strategy supported by the World Bank and African Development Bank to end energy poverty in Zambia) targets investment of $11.9 billion in power by the end of this decade. This includes $9.5 billion from the private sector, supported by a wide range of investment and electricity trading liberalisations.
A new model for power investment
These are ambitious targets and much depends on the readiness and capacity of the state power utility ZESCO to engage with private developers on constructive terms. According to De Carteret, that is already happening. “Zambia clearly recognises that it cannot meet its generation requirements, mining growth ambitions and energy-security objectives from the public balance sheet alone,” he says. “Recent reforms, faster licensing and new private-sector investment frameworks demonstrate a genuine desire to attract private capital. And I believe that ZESCO is the best utility in the region.”
Reform will certainly be necessary to meet Zambia’s generation targets. The country already has 4,722MW of generation capacity. That is up from 3,777MW in 2024, but Zambia is aiming for 10,000MW by 2031 (as of September 2026, 1,315MW of new construction was underway, according to the country’s Energy Regulation Board). Under the National Energy Compact, several policies designed to achieve the 2031 target are already in progress, if not fully rolled out. The Electricity Open Access Framework gives independent power producers (IPPs) access to transmission and distribution networks and allows power trading outside the traditional ZESCO off-taker arrangements. The Energy Single Licensing System, meantime, is intended to simplify and speed the licensing process for IPPs, removing the need for multiple approvals. Equally important is the Multi-Year Tariff Framework, enabling a transition to true-cost tariffs without compromising the finances of the state power utility.
Consistent policies are necessary to underpin investment
In a recent Zambia Economic Update, the World Bank said the financial fragility of ZESCO is at the core of Zambia’s electricity challenge. Yet the planned increase in generation capacity is a practical as well as financial challenge. The transmission grid will need an extensive upgrade to handle increased generation and, although this is recognised in Zambia’s Integrated Resource Plan (IRP) for developing transmission and distribution networks, it is potentially the weak link in Zambia’s power programme.
“Transmission is the choke point,” Sipho Phiri, who chairs Kwama Energy, the co-developer of the Ilute 32MW solar plant near Sesheke in Zambia’s Western Province, told ENN in October. “There’s no point generating power if you can’t move it. Those highways for electrons need to be built and they need to be built with utmost urgency. We are on the verge of melting our power lines as it is, trying to move energy across the region.”
De Carteret agrees that transmission is the area where the risk of disappointment is highest. “Generation is expanding rapidly, but transmission risks are becoming the bottleneck,” he says. “Zambia’s IRP envisages roughly 5,200km of additional transmission by 2030 and approximately $1.4 billion of transmission investment by then. The question is whether grid reinforcement and new transmission can be delivered quickly enough to accommodate the large pipeline of generation projects.”
This is a familiar bind for African policymakers. Overall demand for energy is growing faster in Africa than anywhere else in the world, according to S&P Global Energy, and while standalone generation projects are relatively easy to cost and de-risk, transmission and distribution infrastructure has longer development cycles and involves greater political and project risk.
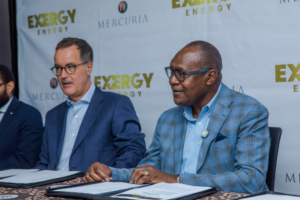
Investors will only allocate capital to core power infrastructure projects in Africa where they are convinced that policy will remain supportive of private investment over the long term. There are some signs that this is already the case in Zambia. For example, the Swiss energy and commodity trader Mercuria recently signed a $250 million financing agreement to develop power generation through Lunzua Power Company and transmission capacity through Lusitu Transmission and Distribution, two Zambian subsidiaries of the Africa-focused energy investor Exergy. The transaction, which is still subject to regulatory approval, is an important sign of investor confidence in the Zambian government’s commitment to facilitating longer-term, higher-risk investment in power.
Effective implementation could put Zambia at the heart of African power transmission
More infrastructure investment is already underway. In October, Gridworks, Trafigura, EnPower and FIS-RDC signed a framework agreement for the 200km, $300 million Kalumbila to Kolwezi interconnector into the DRC Copperbelt, and Axian signed a power purchase agreement for its 200MW Kudu solar plant.
Yet according to De Carteret, there’s still work to be done in giving private power producers fair access to the transmission and distribution network, at a fair price, in an environment of policy predictability.
“Long-term investors can accommodate many emerging-market risks, but unexpected changes to the rules after capital has been committed are harder to accommodate and will keep investors away,” he says. “Investors will place their money in countries who can give them certainty.”